IPO & SPAC Market Update: Q3 2026
Market Normalization Follows a Landmark Quarter
-
October 29, 2026
-

Executive Summary
The third quarter of 2026 marked a return to more normalized initial public offering (“IPO”) market conditions following the transformative impact of the SpaceX offering in the prior quarter. While headline transaction values declined significantly across most markets, this pullback was largely the result of an exceptionally difficult comparison with 2Q26 rather than a deterioration in underlying market fundamentals. IPO activity remained active and issuer participation reflected selective but stable investor demand.
The quarter reflected a sharp shift from the record deal values reported in 2Q26. Investor demand remained selective, favoring companies with strong fundamentals, while issuers continued to navigate an uncertain economic backdrop. Although transaction values retreated from recent highs, issuers across a range of sectors continued to access the public markets, indicating ongoing investor support for well-positioned companies.
U.S. Market Overview
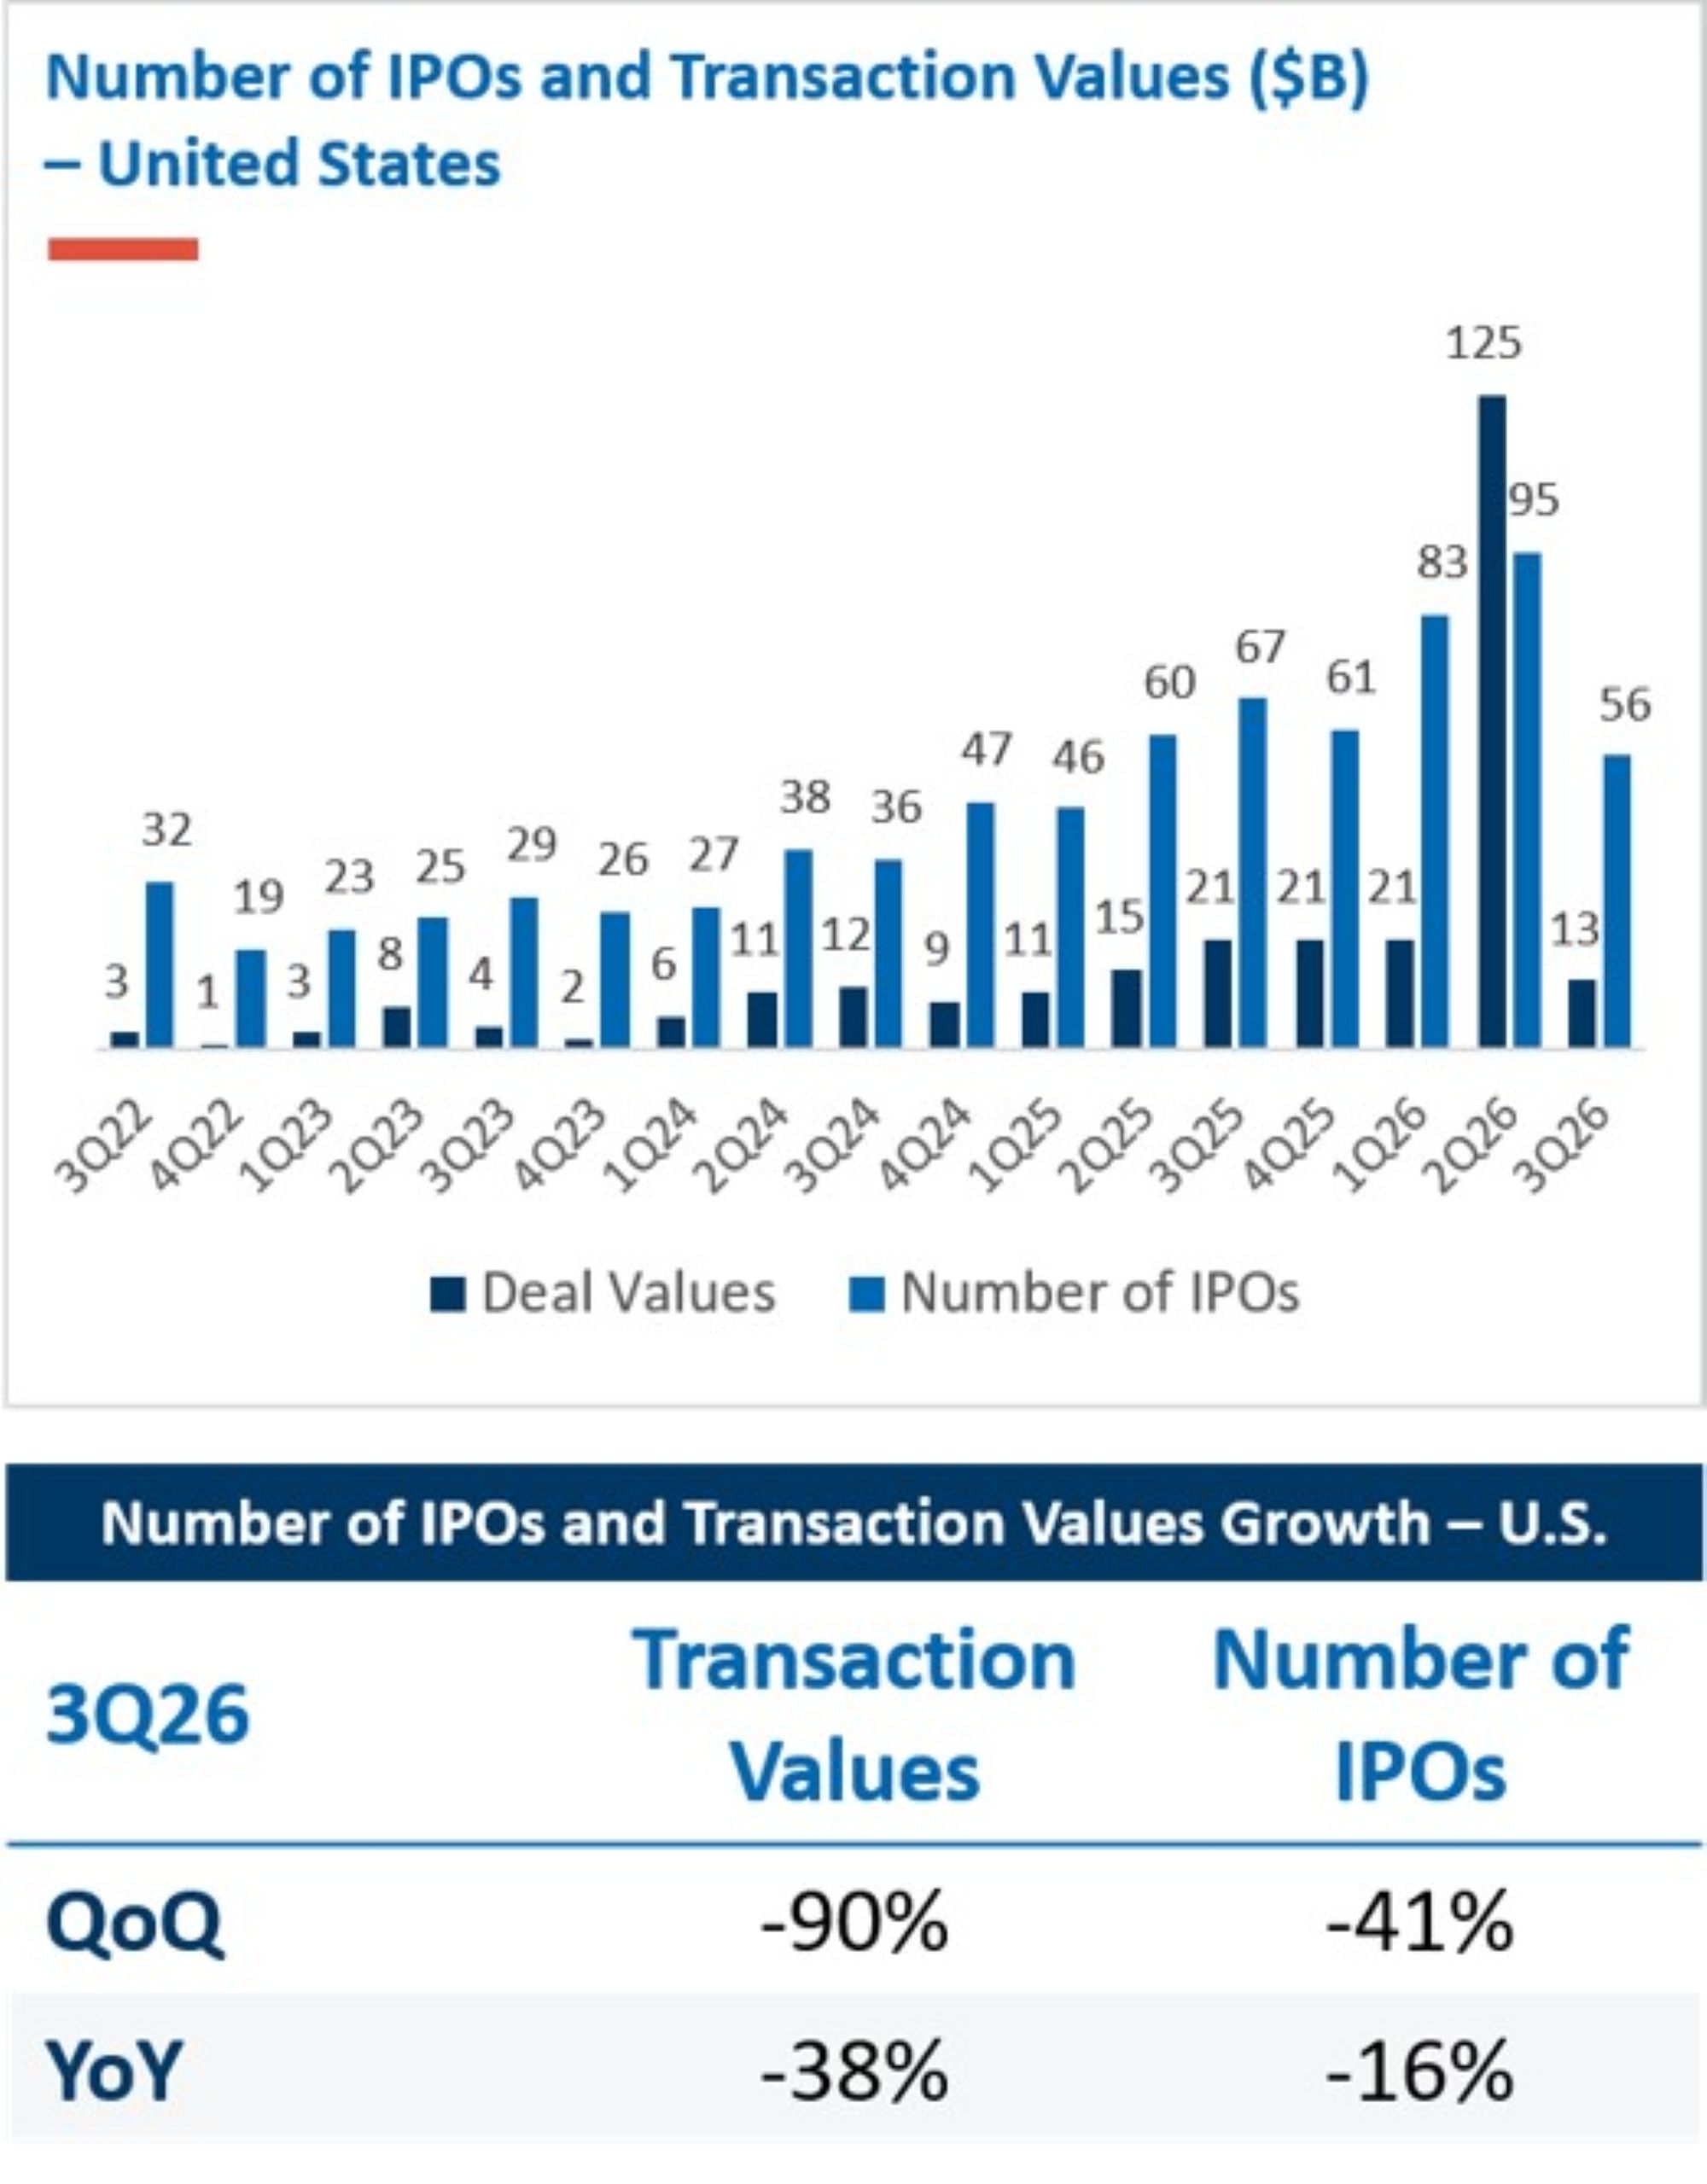
The U.S. IPO market experienced a sharp decline in headline activity during the third quarter as the outsized impact of the SpaceX transaction rolled out of comparative results. Total proceeds fell to approximately $13 billion, representing a 90% decline quarter over quarter and a 38% decrease year over year, while the number of IPOs declined 41% sequentially and 16% compared with the prior year. Transaction values reached their lowest level since 2Q25, highlighting the influence of the SpaceX transaction on the prior-quarter results.
Despite the decline in aggregate metrics, issuance activity remained broad across industries. Several transactions exceeded $500 million, indicating continued investor support for well-positioned issuers. The decline in proceeds primarily reflects the absence of large-scale offerings rather than a meaningful deterioration in market activity.
Figure 1: Number of IPOs and Transaction Values ($B) — United States
Source: FTI Consulting analysis of publicly available and licensed subscription data (2026)
Global Market Overview
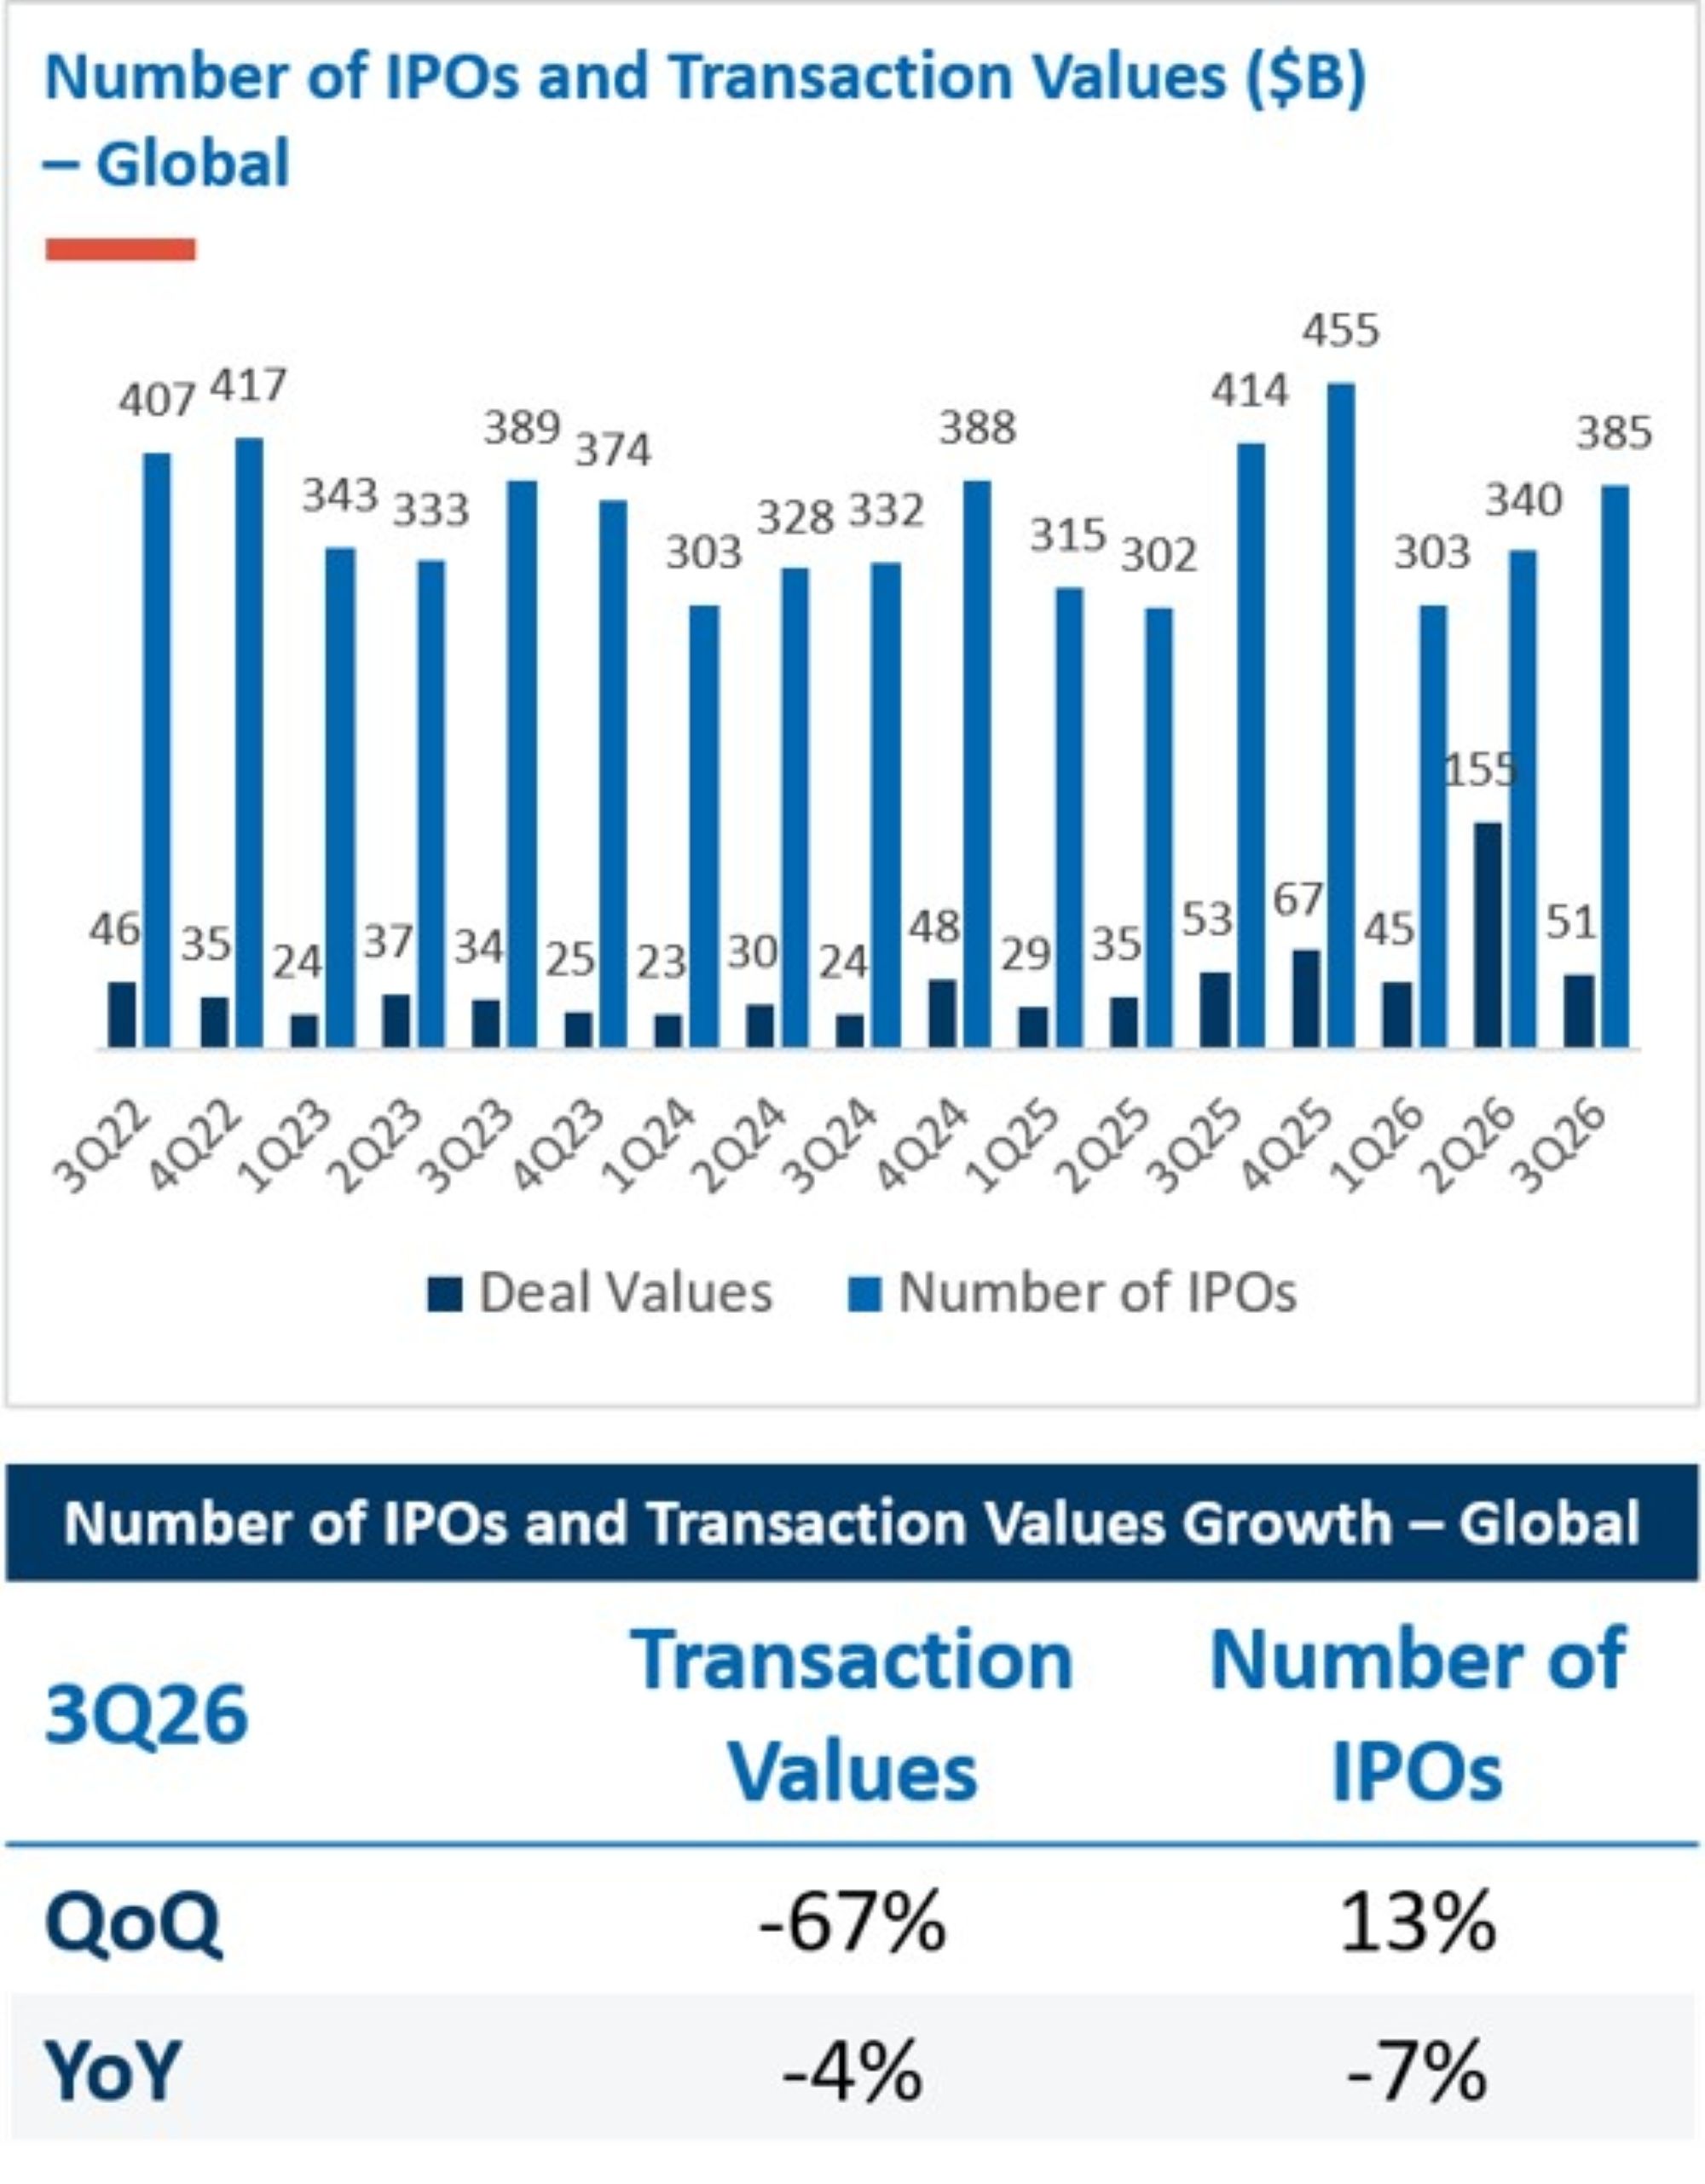
Global IPO markets moderated following the unusually strong second quarter. Total global proceeds reached approximately $51 billion, declining 67% quarter over quarter but remaining broadly consistent with the prior year, down only 4%. Global IPO volume increased 13% sequentially to 385 transactions, although it declined 7% compared with 3Q25. Transaction values normalized following the SpaceX-driven surge, while overall issuance activity remained relatively stable across global markets.
The quarter demonstrated that underlying market activity remains healthier than headline proceeds suggest. Although average deal sizes declined from the prior quarter, issuers continued to access the public markets at a steady pace, supporting higher quarter-over-quarter issuance volumes despite a sharp reduction in capital raised.
The combination of stable IPO volumes and lower transaction values points to a market increasingly driven by a broader mix of issuers rather than a smaller number of transformational offerings.
Figure 2: Number of IPOs and Transaction Values ($B) — Global
Source: FTI Consulting analysis of publicly available and licensed subscription data (2026)
U.S. SPAC vs. Traditional IPO Activity
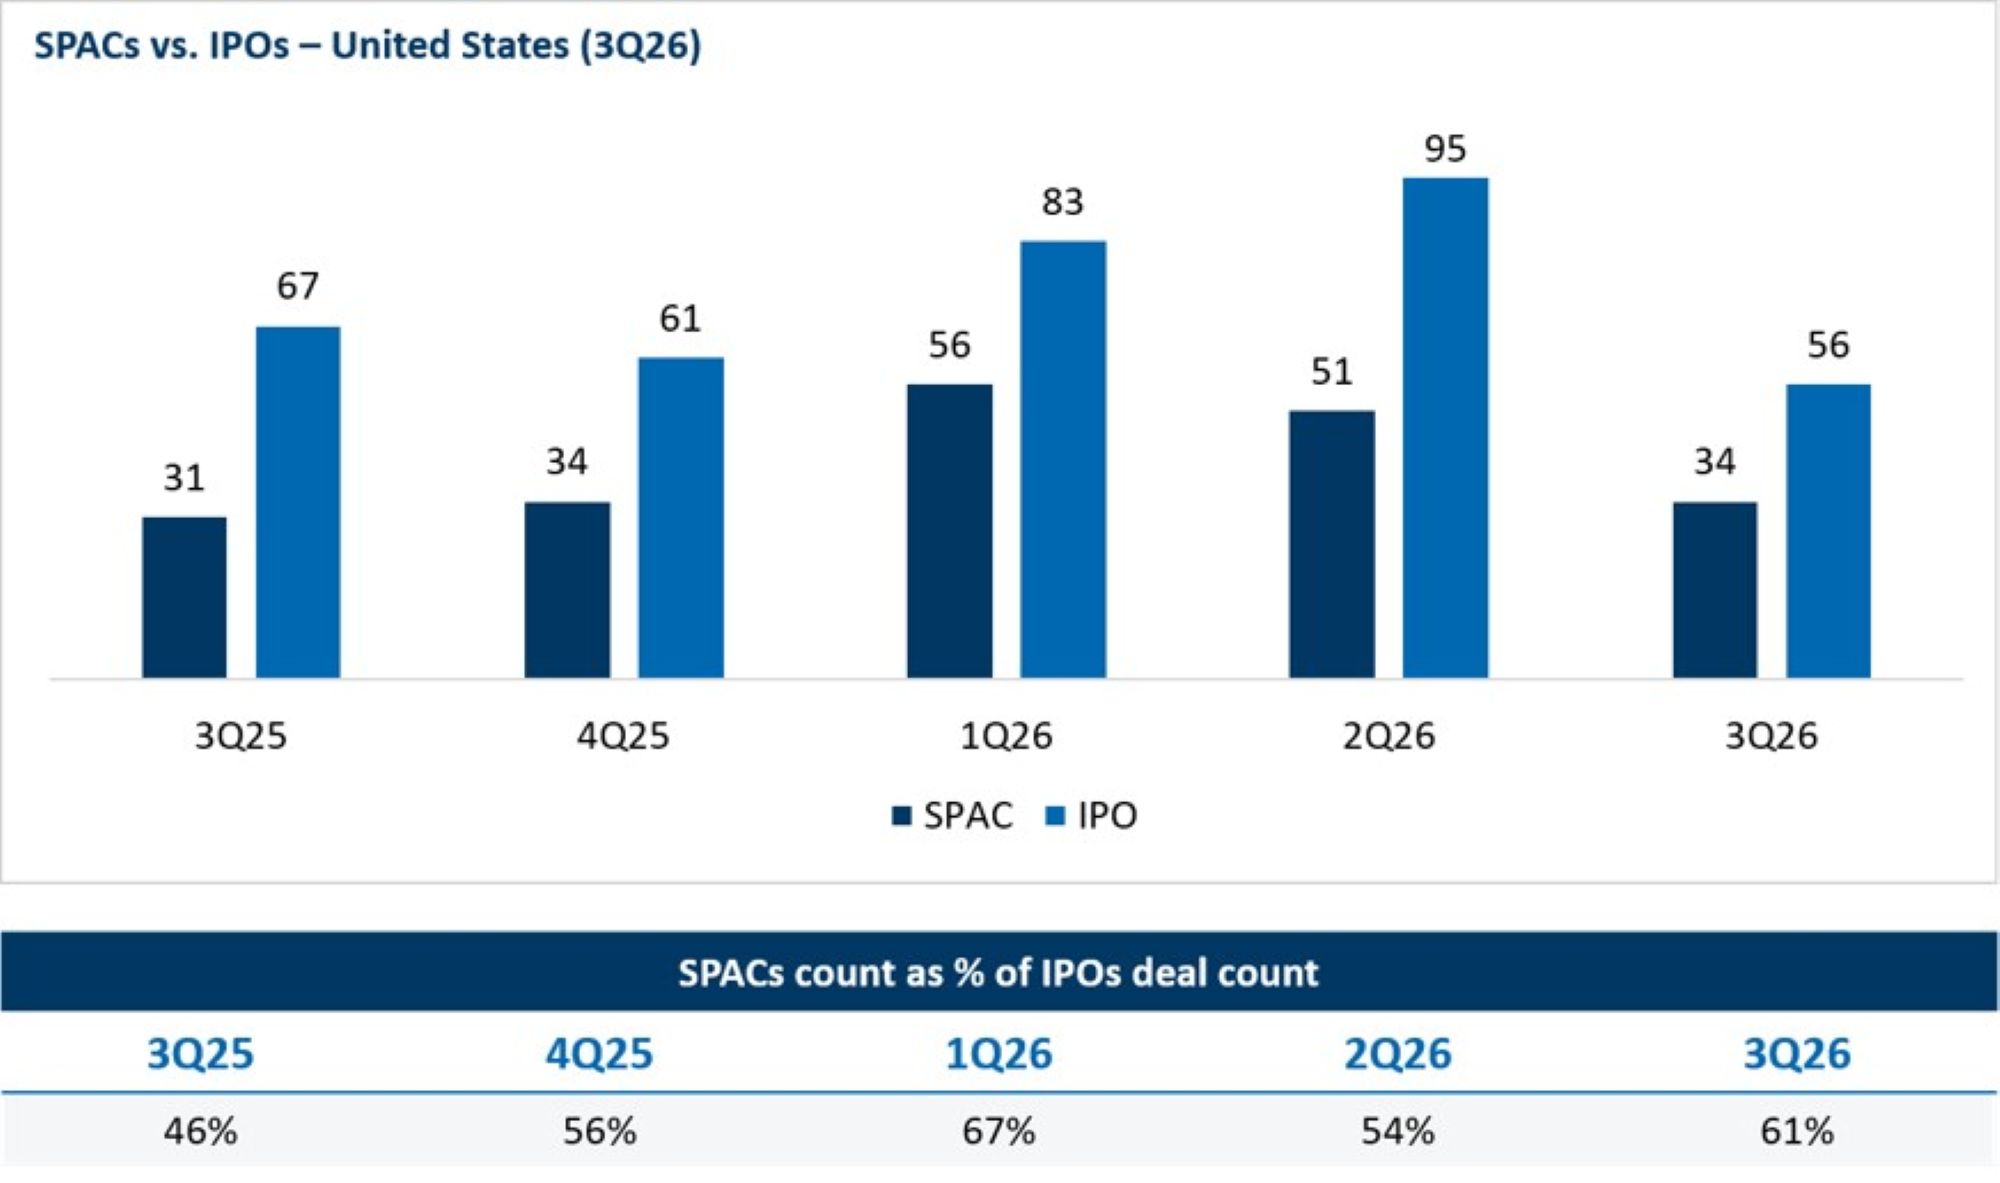
Special purpose acquisition company (“SPAC”) formation remained a meaningful component of U.S. capital markets activity during the third quarter. SPAC formations were equivalent to 61% of traditional U.S. IPO deal count, increasing from 54% in the prior quarter. However, total SPAC formations declined from 51 transactions in 2Q26 to 34 transactions in 3Q26, reflecting the broader slowdown in overall issuance activity. Traditional IPO activity also moderated during the third quarter, declining from 95 offerings in 2Q26 to 56 offerings in 3Q26. As a result, SPACs increased their relative share of total issuance despite lower formation volumes in absolute terms. The increase in SPAC market share reflects weaker traditional IPO activity rather than stronger SPAC formation.
Traditional IPOs and SPACs remained active during the quarter. While traditional IPO issuance remained well above levels seen one year ago, sustained SPAC activity indicates that sponsors and issuers continue to view alternative structures as viable routes to the public markets.
Figure 3: SPACs vs. IPOs — United States (3Q26)
Source: FTI Consulting analysis of publicly available and licensed subscription data (2026)
Sector and Regional Highlights
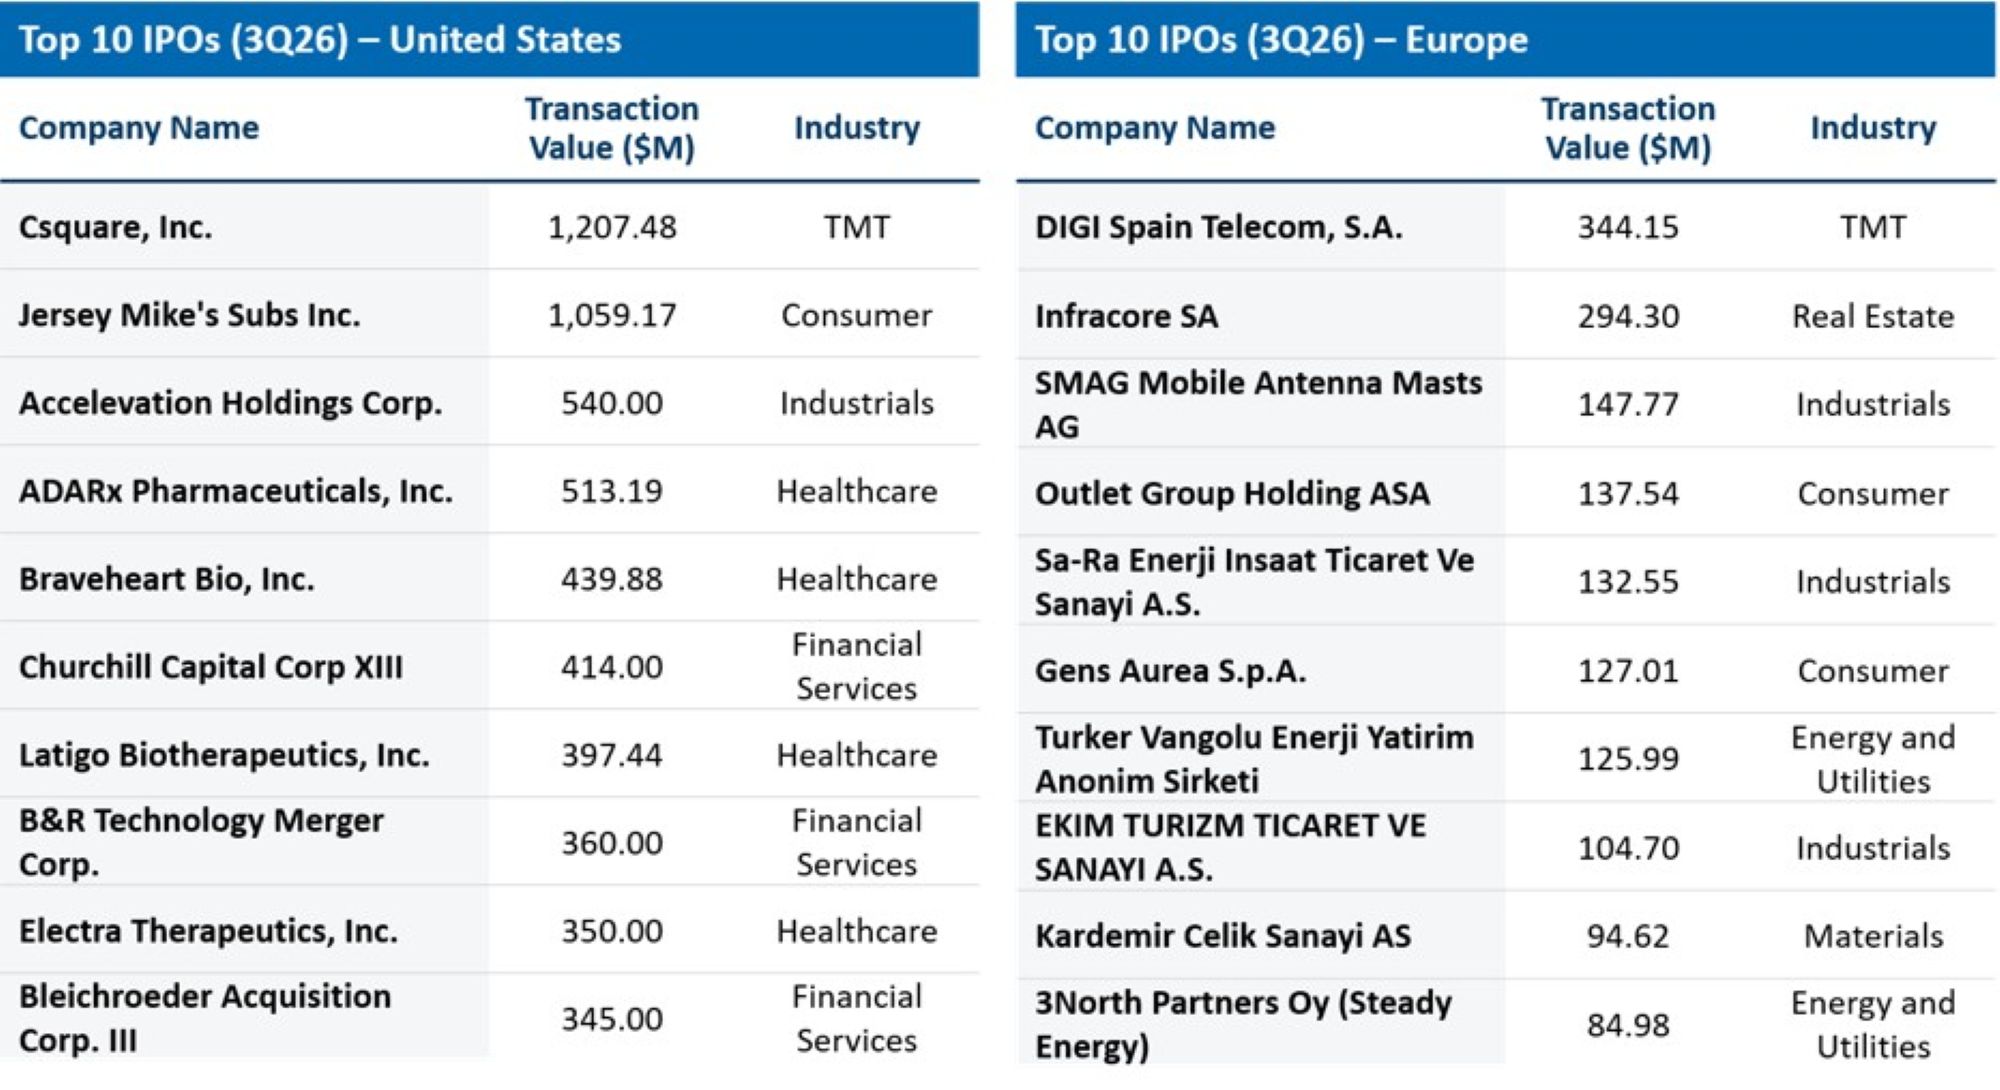
Telecom, Media & Technology (“TMT”) produced the largest IPOs in both the United States and Europe during the third quarter, reflecting investor interest in technology-focused issuers. In the United States, Csquare, Inc.’s approximately $1.2 billion offering led all new issuances during the quarter and was the only billion-dollar transaction among the largest deals.
Healthcare accounted for 40% of the top-10 U.S. IPOs by count, while Financial Services represented 30%, reflecting continued investor interest in both sectors. The quarter’s largest transaction came from the TMT sector, reinforcing the sector’s position as a leading source of IPO activity.
European activity mirrored trends observed in prior quarters, with Industrials continuing to account for a significant portion of the region’s largest transactions. Similar to the United States, however, the largest European IPO originated from the TMT sector. The average transaction value among the top-10 U.S. IPOs remained approximately 3.5 times larger than comparable European offerings, underscoring the depth of U.S. capital markets.
Figure 4: Top 10 IPOs (3Q26) — United States & Europe
Source: FTI Consulting analysis of publicly available and licensed subscription data (2026)
Looking Ahead
The third quarter reinforced that the extraordinary results recorded in 2Q26 were largely driven by a single transaction. As IPO markets normalize, investors appear increasingly focused on issuer quality and long-term growth prospects.
Attention will center on whether increasing European issuance translates into larger offerings and whether U.S. IPO activity settles into a more sustainable pattern following the second quarter’s surge. Macroeconomic conditions remain an important consideration for both issuers and investors. Issuers with strong fundamentals and clear market positioning continue to find opportunities to access the public markets.
The third quarter marked a return to more typical market conditions following the surge in activity recorded in 2Q26. While transaction values and issuance moderated, activity remained healthy across both traditional IPOs and SPACs. Continued issuer participation suggests public markets remain open for companies with strong fundamentals and clear market positioning.
The views expressed herein are those of the author(s) and not necessarily the views of FTI Consulting, Inc., its management, its subsidiaries, its affiliates, or its other professionals.
Related Insights
Published
October 29, 2026
 Key Contacts
Senior Managing Director, Global Head of M&A
Senior Managing Director, Co-Leader of SEC Accounting & Advisory
Senior Managing Director, Co-Leader of SEC Accounting & Advisory
Senior Managing Director