


The Payment Hub as a Bank Accelerator: Turning Optionality Into Execution
-
October 27, 2026
-

A payment hub can convert a bank’s payment-rail strategy into a common processing and operating model, accelerating how the institution launches products, applies controls and supports new payment types.
Payment hubs are often justified as technology consolidations, but their more strategic value is execution speed. They can turn the shared capabilities required for payment optionality into a practical operating surface, allowing a bank to launch a product, update a policy or connect a new payment type in weeks rather than years. That value is realized only when governance, processes and people are redesigned to move at the pace the platform allows.
From Payment Optionality to Payment-Hub Execution
Banks increasingly expect to operate across traditional rails, instant payments and emerging settlement models at the same time. The companion article, “Why Payment Optionality Is Now a Strategic Imperative,” explains why a bank’s leadership should invest in reusable, rail-agnostic capabilities rather than bet on a single winning infrastructure. This article takes the next step: explaining how a payment hub can implement that strategy through common intake, processing, controls and connectivity.
Exhibit 1: No Payment Type Rail Is Retiring: The Bank Has to Be Good at All of Them at Once
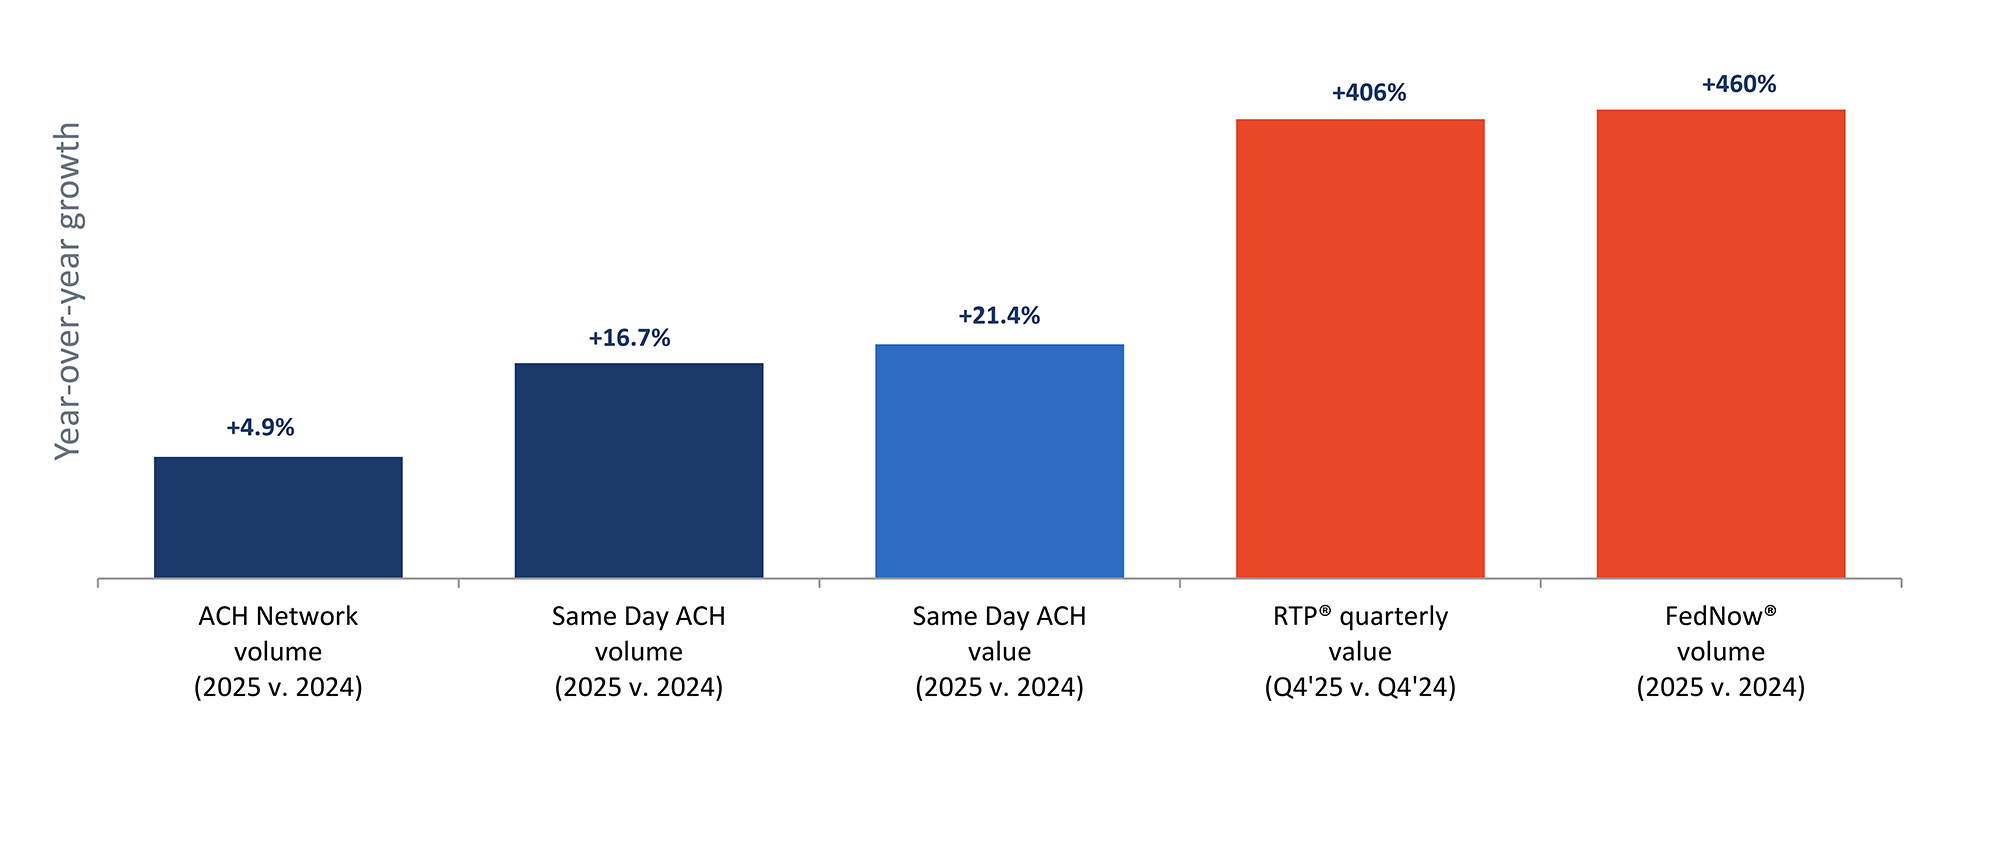
Batch volume is still compounding off an enormous base while instant payment type rails grow off a small one. A siloed payment type rail operating model has no mechanism for absorbing both curves at the same time. Percentages measure different bases and are directional.1
How a Payment Hub Implements the Strategy
A banking payment hub centrally processes an institution’s incoming and outgoing payments across high-value, batch, real-time and increasingly alternative settlement methods, including stablecoins. In implementation terms, it provides a common control plane and operating surface for capabilities that would otherwise be rebuilt rail by rail. Gartner describes an architecture that moves from on-premises monoliths toward composable, cloud-based software organized in three layers.2
- Input. Accepts requests from any channel (digital and mobile banking, corporate host-to-host files, core banking, treasury systems, partner APIs) and validates, normalizes and, where necessary, translates or repairs them before anything moves.
- Processing. Provides reachability and routing, duplicate and balance checks, fees, FX and value dating, the orchestration of sanctions, anti-money laundering and fraud screening. This is where the institution’s policy lives.
- Output. Formats to network/scheme specifications, settles, generates the accounting entries and produces the audit trail. New payment type rails attach here. The broader adoption of ISO 20022 also creates an opportunity to normalize payment data across networks, making common controls, routing and exception management more practical than they were when each rail evolved independently.
The Implementation Constraint: Payments Is Still Organized Around Its Plumbing
Ask a bank how it is organized and you will hear about consumer, commercial, wealth and markets. Ask how payments are organized and you will hear about wires, ACH, instant, cross-border, and cards. Payments are often still structured around the payment type rails they run on rather than the clients they serve: an arrangement of operational silos, each with its own intake logic, screening configuration, exception queue, vendor contract and staff who know one scheme well and the others not at all.
That structure was rational when it was built, since each payment type rail arrived a decade apart, funded by a different sponsor and bolted on where it could fit. It gets expensive when the institution must explain an outcome across payment type rails, serve a client who uses four of them, absorb a volume spike on one while another is quiet or prove control effectiveness to a regulator in real time rather than in a quarterly pack.
A payment hub can be a direct way to consolidate those silos without losing the expertise inside them, but the platform alone will not do so. The implementation case should therefore be built around measurable changes in speed, reuse, control consistency and operating flexibility. License reduction and infrastructure savings can support the business case, but they should not obscure the organizational changes required to realize the value.
The payment hub upside shows up in three places:
These benefits should be treated as implementation outcomes, with baselines, owners and target dates established before migration begins.
- Shorter deployment cycles: Product and payment type launches that once took a year of point-to-point integration become weeks of configuration.
- Customer stickiness: Clients who might otherwise take a payment type elsewhere stay, because the bank can support it without a separate build.
- Flexible operational capacity: The same analysts who handle a wire exception can absorb an instant payment spike, rather than each payment type needing its own dedicated staff.
Implementation Choice: Hub or Best-of-Breed
The best-of-breed debate is usually run as a functionality bake-off, which is why it rarely resolves to satisfaction. Point solutions optimize throughput inside a payment type rail and tend to reproduce a silo structure in software: five strong engines, five policy configurations, five operational consoles, five vendor roadmaps to align. Those are modern silos, but they are still silos. Composability means a hub no longer implies a monolith, since components can be replaced without re-platforming, so the question is whether the modules sit inside one control plane and one operating surface.3 Two tests settle it. When policy changes, does it reach every payment type rail at once, and can one trained analyst work any queue on the floor?
Technology is the enabler. The implementation objective is a shared control plane and operating surface that standardizes what should be common, preserves what must remain rail-specific and allows new capabilities to be added without recreating the organization around each rail.
Is Your Organization Ready to Implement Acceleration?
Payment optionality defines the strategic destination: an institution able to deliver customer outcomes across multiple rails and settlement models. A payment hub is one way to implement that direction. Its value lies in converting reusable capabilities into faster launches, consistent controls, common data and flexible operations, not simply in replacing infrastructure.
Three questions assess whether an institution is positioned to use the acceleration it is paying for.
These questions intentionally follow the strategic choices addressed in the optionality article. They test whether the selected implementation model is converting enterprise direction into client and operating outcomes.
- How long does it take to add a new payment type, from business case approval to go-live?
- How many clients has the bank lost, or nearly lost, because a competitor could support a payment type it could not?
- How much of the platform’s speed actually reaches the client, versus getting absorbed by approvals, handoffs and exception queues along the way?
If the honest answers are “too long,” “more than we’d like to admit,” and “not much,” the bank has bought an accelerator it is not leveraging.
The institutions that pull ahead will not be those that simply selected the fastest platform. They will be those that sequenced implementation around priority customer journeys, redesigned decision rights and exception handling, trained teams across queues and measured whether platform speed reaches the client. In that operating environment, adding a payment type can become a matter of configuration and controlled integration rather than a multiyear program.
How FTI Consulting Can Help
- FTI Consulting helps financial institutions turn payment hub speed into payment hub results, across Payments, Technology, Operations, Risk, Compliance and Finance.
- Operating model design. Define the target operating surface, one exception desk, one control library, one payment data model, one skill profile and one roadmap owner, before the technology procurement is finalized.
- Hub versus best-of-breed assessment. Apply a control-plane and operating-surface lens to the make-or-buy decision, so the platform choice is driven by organizational fit rather than a feature bake-off.
- Workforce and capacity redesign. Redesign roles, training and staffing models so any trained analyst can work any queue and build the flexible-capacity case the investment committee needs to see.
- Staged capital planning. Sequence the migration into self-funding waves, retire engines in order of operational pain, and stand up the target operating model on the first payment type rail that lands.
- Governance and metrics. Move payments to enterprise ownership with a named owner and end-to-end metrics, including straight-through processing, exception rate by root cause, cost per payment and time to add a payment type rail, measured across the institution rather than per silo.
Footnotes:
1: Nacha ACH Network 2025 results, January 2026 (35.2bn payments; $93tn value); Fiserv analysis of The Clearing House RTP® Q4 2025 value ($405bn v. $80bn a year earlier); Federal Reserve FedNow® 2025 volume growth. Bases differ by measure. Graphic produced by FTI Consulting.
2: Peter Ryan and Debbie Buckland, “Market Overview for Banking Payment Hub Platforms,” Gartner (Aug. 28, 2026), (market definition and three-layer architecture; paraphrased).
3: Ibid.
The views expressed herein are those of the author(s) and not necessarily the views of FTI Consulting, Inc., its management, its subsidiaries, its affiliates, or its other professionals.
Related Insights
Related Information
Published
October 27, 2026
 Key Contacts
Senior Managing Director
Managing Director
Managing Director
Senior Director