

Global M&A Q3 2026 Market Update
Deal Volume Softens as Financial Buyers Gain Share
-
October 26, 2026
-

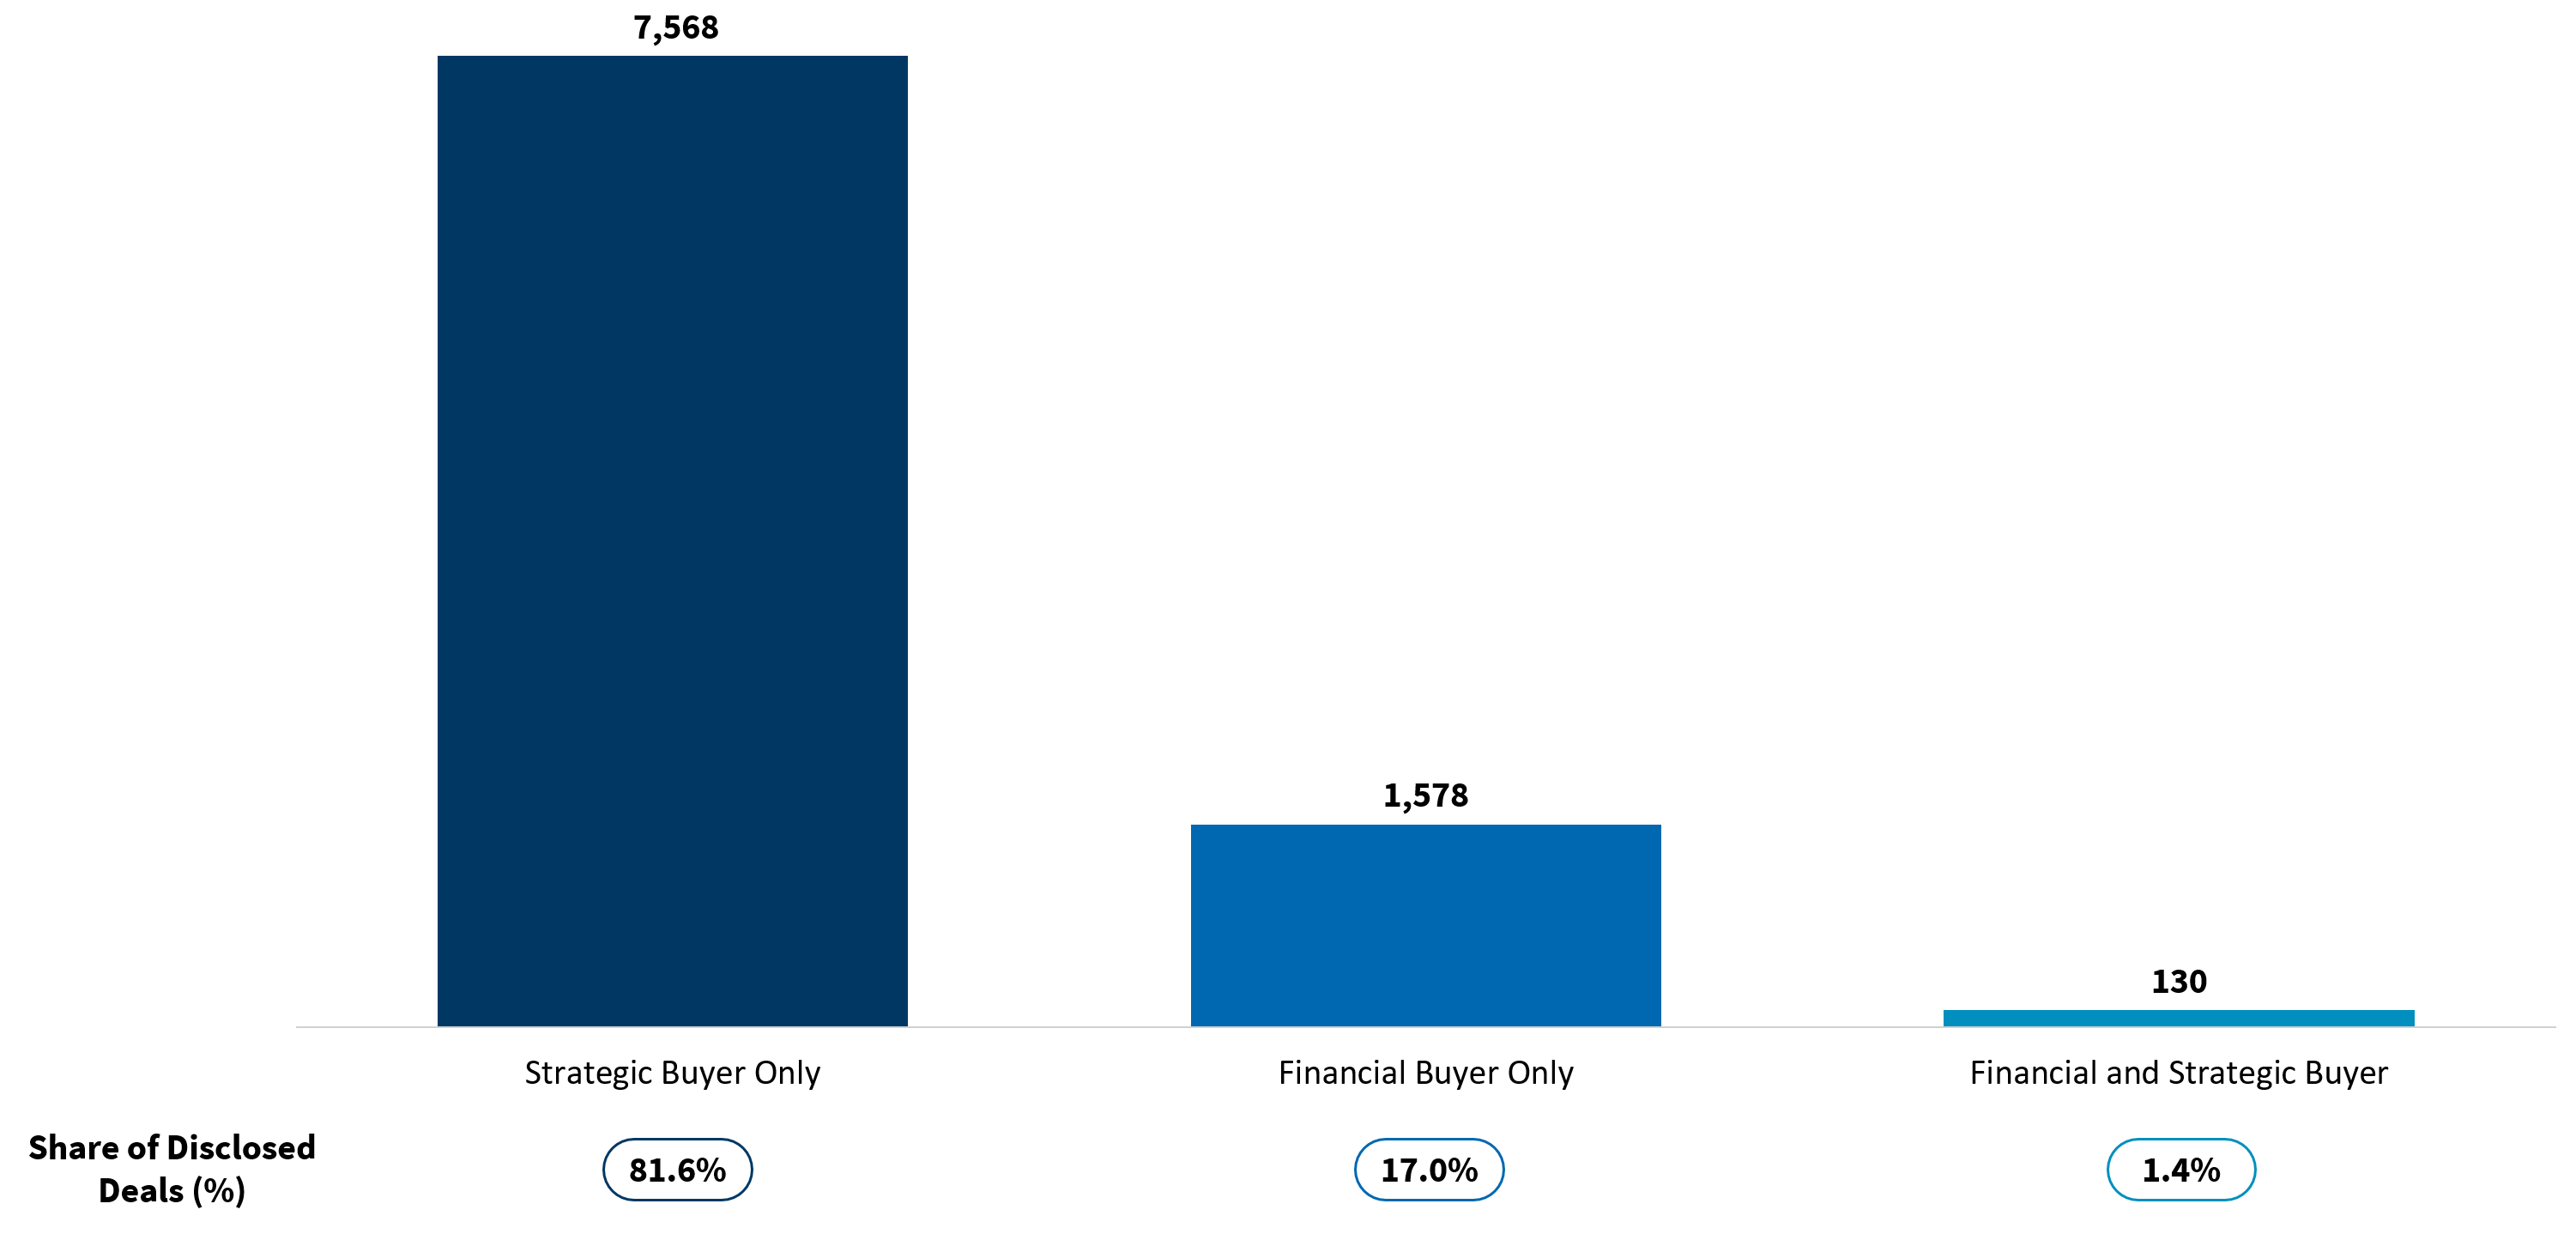
Global M&A activity softened further in the third quarter of 2026, with disclosed deal volume declining 3.7% quarter over quarter and 14.2% year over year to 9,902 announced transactions. Strategic buyers remained the dominant acquirer group, accounting for 81.6% of global disclosed transactions, while financial buyers increased their share to 17.0% from 15.1% in the second quarter.
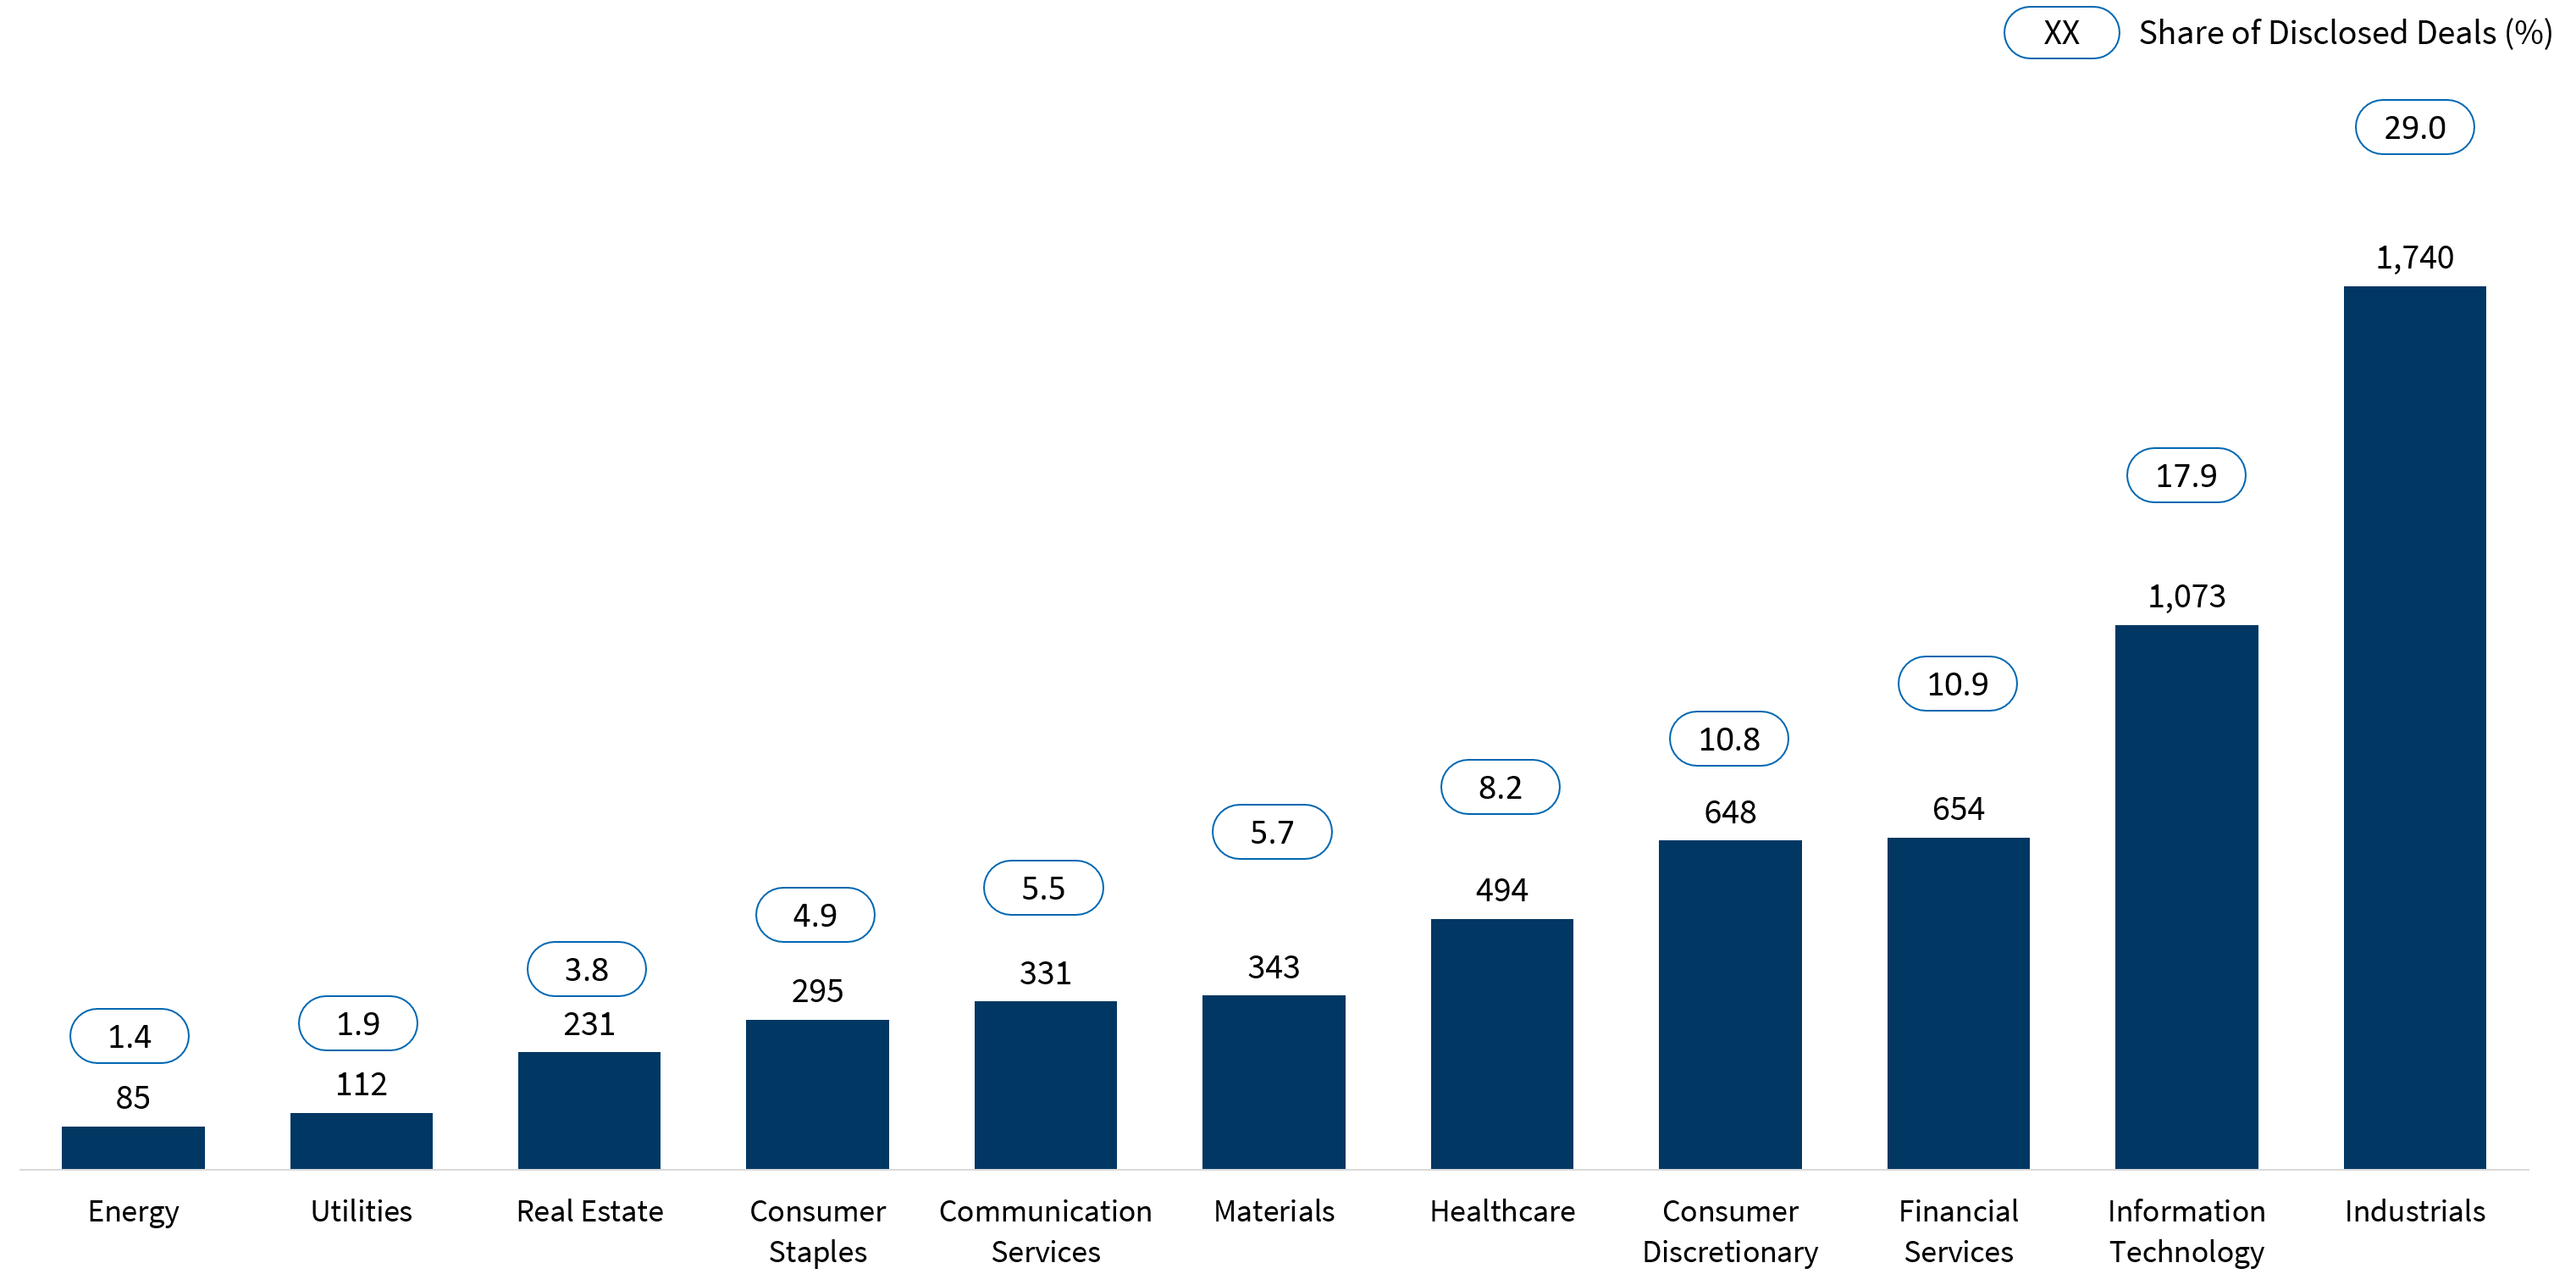
Sector activity also weakened, with disclosed deal volume declining quarter over quarter in 10 of 11 sectors. Industrials, Information Technology and Financial Services continued to account for most sector-classified activity, while transactions below $50 million represented the majority of deals with disclosed transaction values. Together, these trends point to a selective M&A environment in which overall activity remains subdued even as financial buyer participation increases.
Global Market Overview
Strategic buyers remained the primary drivers of global M&A activity during the third quarter, accounting for 81.6% of disclosed transactions. Financial buyers represented 17.0% of disclosed transactions, up from 15.1% in the second quarter, while transactions involving both strategic and financial buyers accounted for 1.4%.
Notably, financial buyer-only transactions increased from 1,453 in the second quarter to 1,578 in the third quarter, even as overall global deal volume declined. This suggests financial buyers became more active during the quarter despite a softer overall M&A environment.
Figure 1 – Disclosed Deal Count by Acquirer Type (#), 3Q26
Source: Capital IQ, FTI Consulting analysis
Sector Performance – Volume
Industrials remained the most active sector globally in the third quarter, accounting for 29.0% of disclosed sector-classified transactions, followed by Information Technology at 17.9% and Financial Services at 10.9%. Together, these three sectors accounted for 57.7% of global sector-classified deal activity.
Figure 2 – Disclosed Deal Count by Sector (#), 3Q26
Source: Capital IQ, FTI Consulting analysis
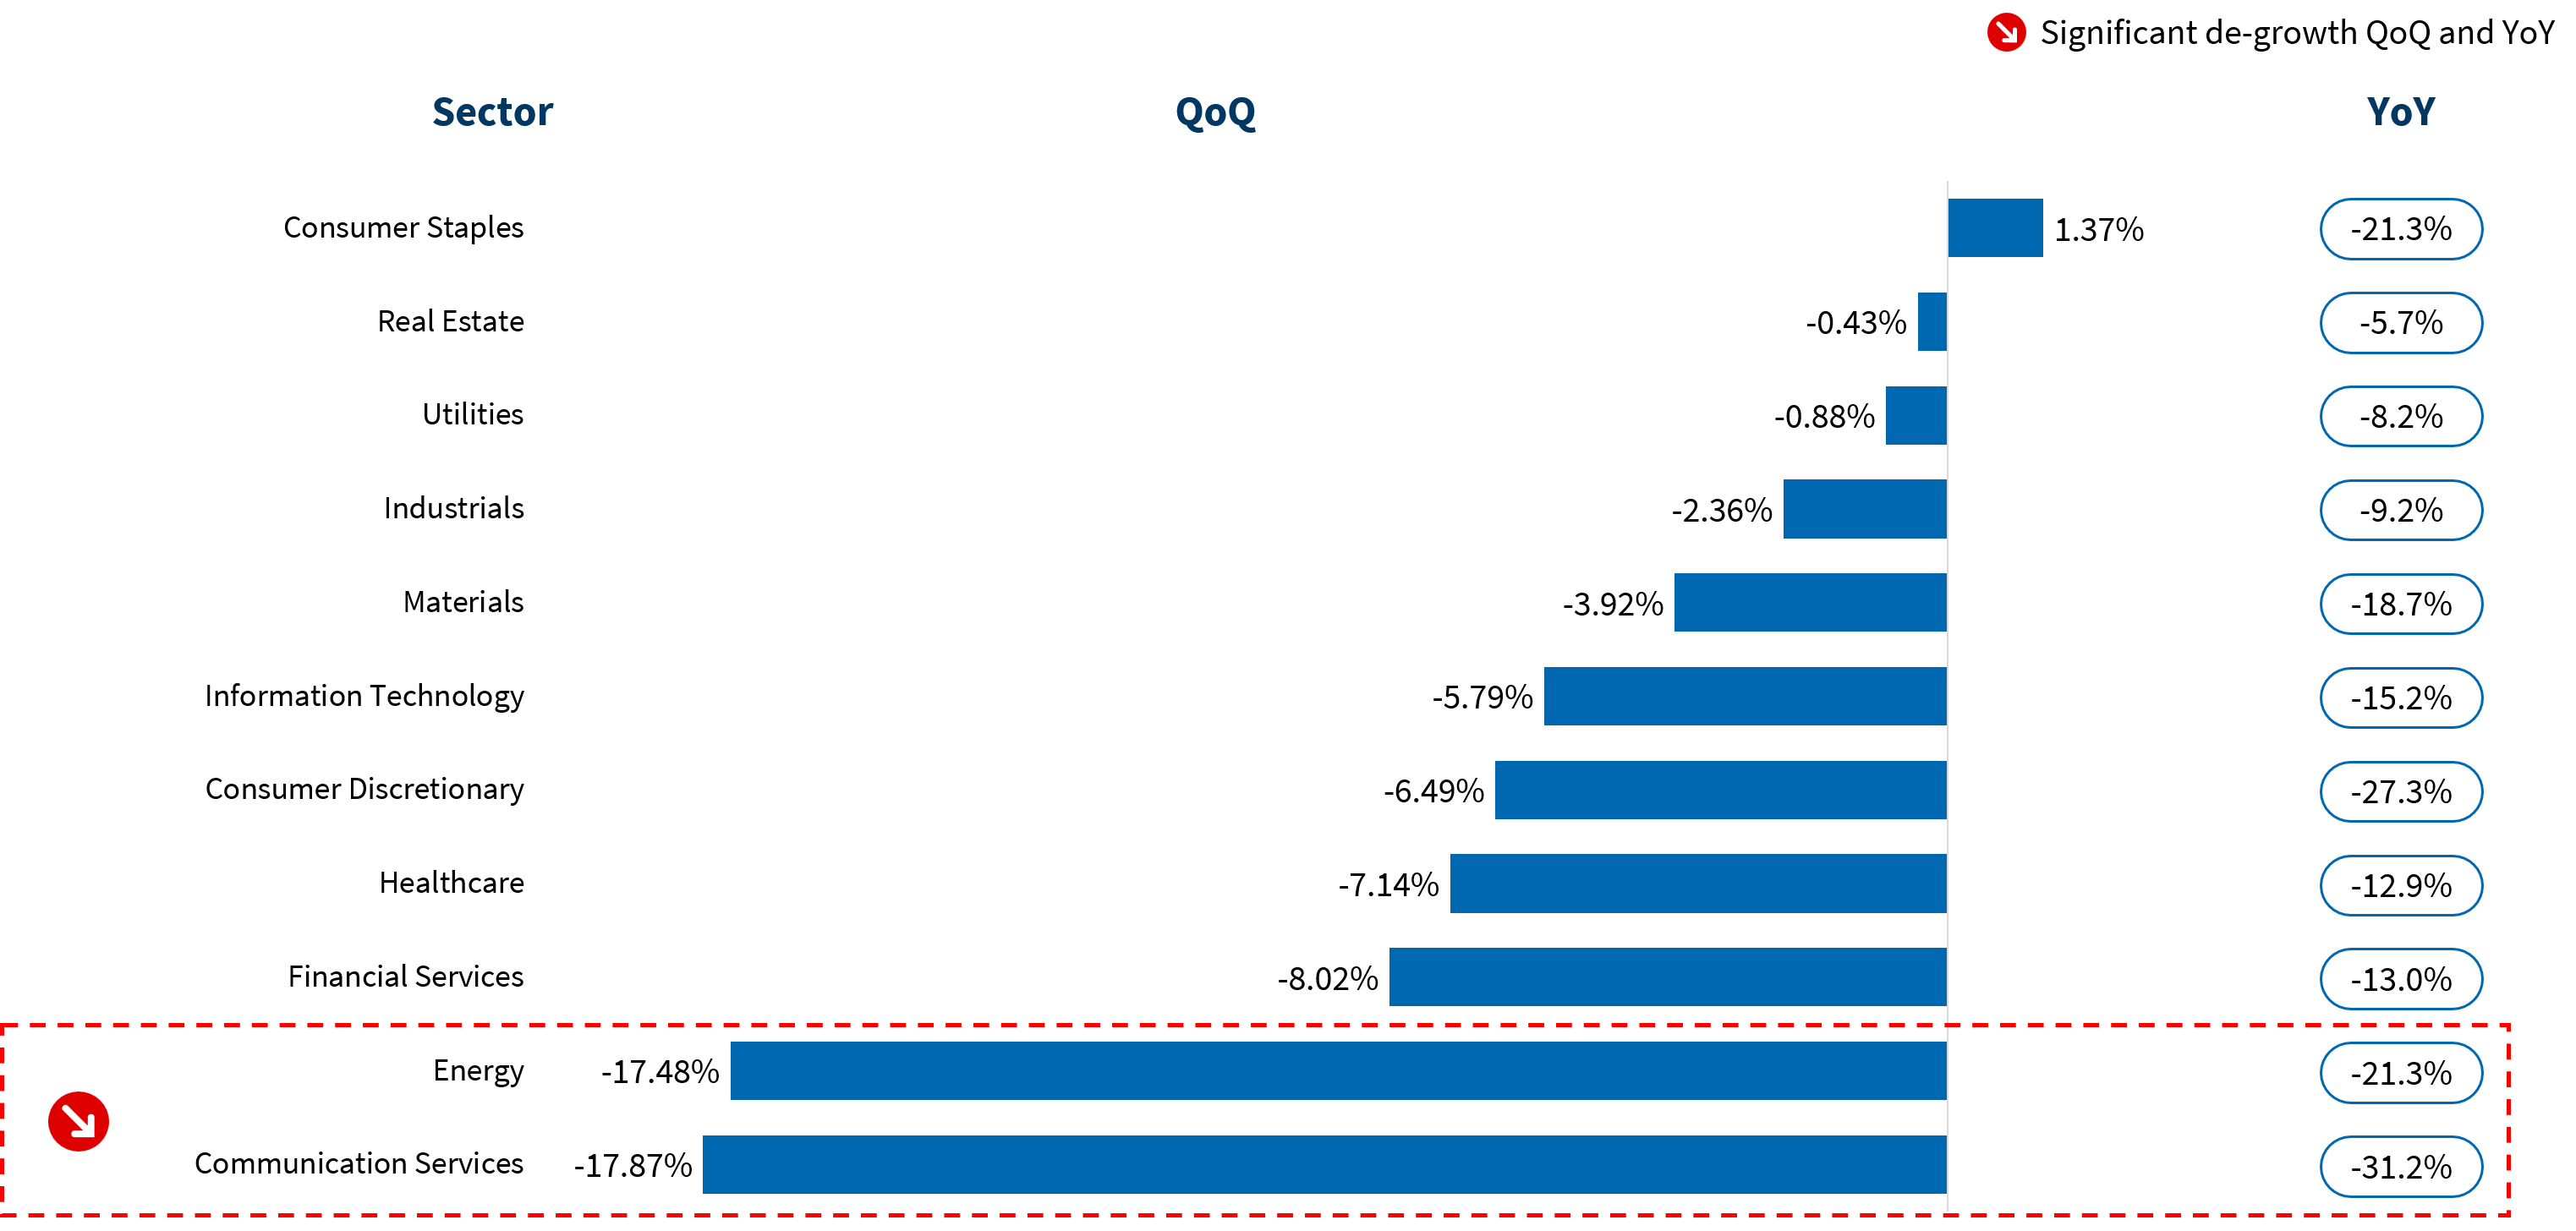
Quarter-over-quarter performance weakened across nearly every sector. Consumer Staples was the only sector to increase disclosed deal count, up 1.4%. Communication Services (-17.9%), Energy (-17.5%) and Financial Services (-8.0%) recorded the largest declines, underscoring the absence of broad-based momentum across the M&A market.
Figure 3 – Change in Disclosed Deal Count by Sector (%), 3Q26
Source: Capital IQ, FTI Consulting analysis
Sector Performance – Value
Several large, announced transactions punctuated the third quarter despite softer overall deal volume. In Financial Services, Banca Monte dei Paschi di Siena announced proposed acquisitions of Banco BPM and Banca Generali, with reported transaction values of $32.3 billion and $10.8 billion, respectively. Another notable transaction included Circle K Polska’s proposed $11.3 billion acquisition of Zabka Group.
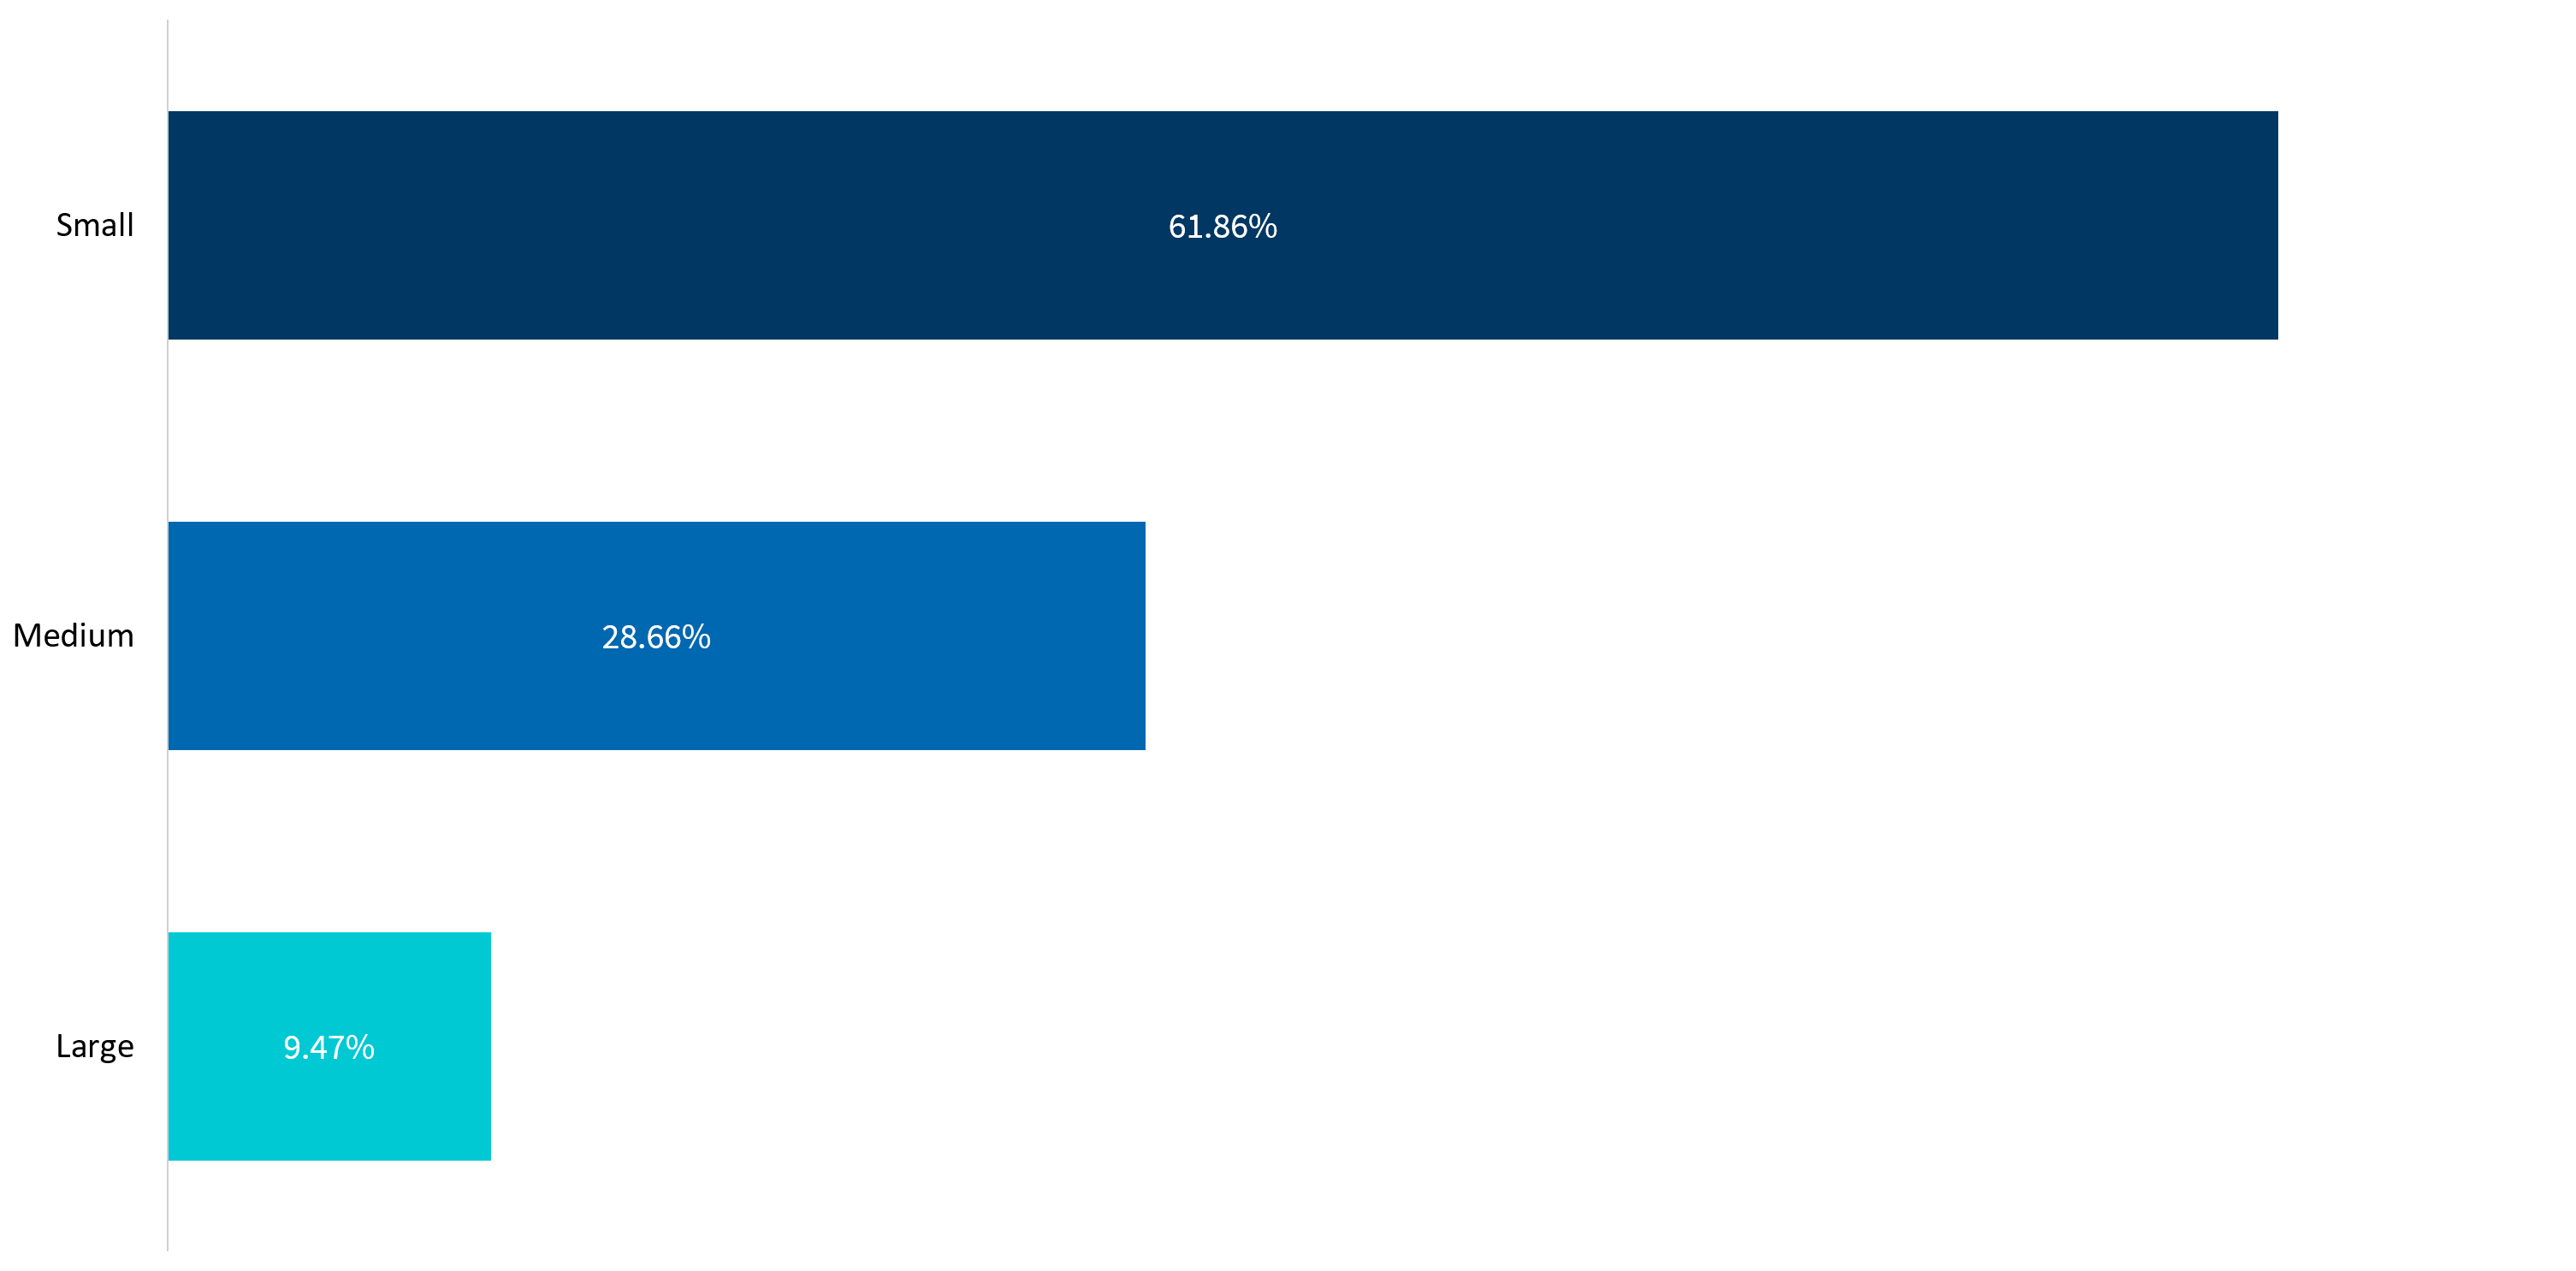
Smaller transactions still accounted for most global M&A activity. Transactions valued at less than $50 million represented 61.9% of deals with disclosed transaction values, while medium-sized transactions of $50 million to less than $500 million accounted for 28.7%. Large transactions of $500 million or more represented 9.5%.
Compared with the second quarter, the transaction mix shifted toward medium-sized deals, which increased from 25.1% to 28.7% of disclosed activity. Small and large transactions accounted for smaller shares of the overall mix.
Figure 4 – Share of Deals by Transaction Size (%), 3Q26
Source: Capital IQ, FTI Consulting analysis
Looking Ahead
Global M&A activity remained selective during the third quarter, with overall deal volume declining for a fourth consecutive quarter. Strategic buyers continued to account for most activity, while financial buyers increased both their share and number of disclosed transactions. Sector performance also remained uneven, with deal volume declining across nearly every sector.
As the market enters the final quarter of 2026, key themes to monitor include:
- Whether global deal activity begins to stabilize following four consecutive quarterly declines
- Whether financial buyer participation continues to increase and how that affects competitive dynamics in transaction processes
- Whether weakness in sector-level deal activity becomes less broad-based
- Whether the shift toward medium-sized transactions persists into 2027
Definitions
Deal count and transaction figures are sourced from Capital IQ and reflect data as of this report’s publication date. Capital IQ periodically refreshes its dataset as deals are reclassified or newly disclosed, which can cause historical figures cited in this report, including prior-quarter comparisons, to differ slightly from those published in earlier FTI Consulting reports. This reflects a data refresh, not a change in methodology. Domestic transactions are transactions in which both the target and buyer are incorporated in the same country. Cross-border transactions are transactions in which the target and buyer are incorporated in different countries. Global transactions are transactions spanning major world regions, including North America, Europe, Asia, Africa, the Middle East, Latin America and the Caribbean. Deal size categories are defined as follows: Small transactions are less than $50 million, medium transactions are $50 million to less than $500 million and large transactions are $500 million or greater. Cancelled transactions are excluded. Transactions not classified within a specific industry sector are included in overall totals.
The views expressed herein are those of the author(s) and not necessarily the views of FTI Consulting, Inc., its management, its subsidiaries, its affiliates, or its other professionals.
Related Insights
Published
October 26, 2026
 Key Contacts
Senior Managing Director, Global Head of M&A
Senior Managing Director, Leader of Merger Integration & Carve-Outs
Senior Managing Director, Leader of Financial Due Diligence